


Executive Summary
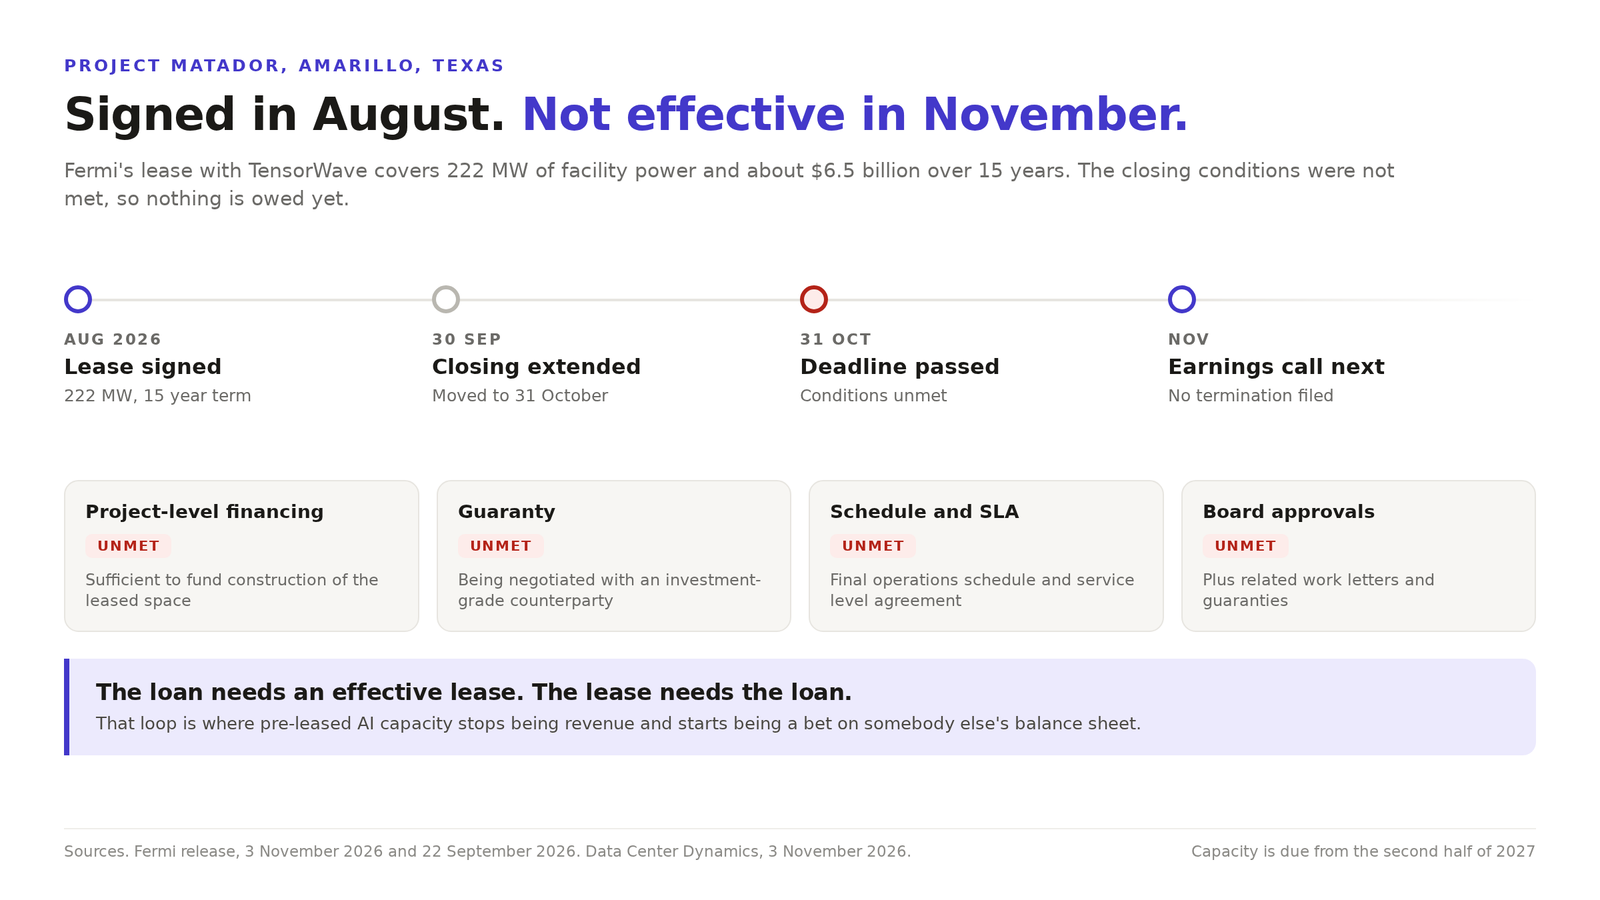
Fermi’s lease with TensorWave was signed in August and has still not taken effect. The 31 October closing date passed with four conditions outstanding, and the largest is project-level financing to fund construction. Nothing is owed until those conditions are satisfied, which turns a headline value of about 6.5 billion dollars over 15 years into an option rather than revenue.
This is the clearest test case yet for how pre-leased AI capacity actually works. The developer needs construction debt, the lender wants an effective lease, and the lease needs the debt. That loop closes only when a guarantor steps in. For anyone buying capacity at a campus that does not yet exist, the number to check is not the megawatts in the release. It is how many closing conditions are still open, and who is standing behind them.
Fermi America told investors on Tuesday that its Data Center Lease and Services Agreement with TensorWave did not close by 31 October. The lease has not become effective. Neither side has exercised a termination right, and the company pointed to its earnings call next week for more.
The scope is not small. TensorWave leased 222 megawatts of facility power at Project Matador, the campus Fermi is building near Amarillo. Capacity is due from the second half of 2027, with rights to expand into two more data centers totaling 650 megawatts, according to Data Center Dynamics. Fermi put the deal at about 6.5 billion dollars of revenue across its initial 15 year term when it extended the closing in September.
The condition that failed was not demand. Fermi’s statement lists four. Work letters and guaranties, a final operations schedule and service level agreement, board approvals, and project-level financing sufficient to fund construction of the leased space. None were satisfied by the deadline. Fermi says it is still negotiating a guaranty of the lease obligations with an investment-grade counterparty.
A condition precedent is a deadline dressed as paperwork
Until those items clear, the lease does no work. No rent starts, no capacity transfers, no obligation lands on the tenant’s balance sheet. The 6.5 billion is a forecast rather than backlog, and the company’s own wording says as much by calling the lease ineffective.
Fermi is a thin company carrying a very large plan. It has about 1.5 billion dollars already in the Matador site, and it went public in October 2025 at a 15 billion dollar valuation without a single server live. A prospective tenant walked away from a 150 million dollar lease in December. The campus has grown from 11 gigawatts announced to 17 gigawatts planned, and the building is being financed against leases that have not closed yet.
The financing sits on the campus, and the campus does not exist
This is the ordering problem in every pre-leased AI campus, and it is the part of data center lease financing that rarely appears in the announcement. A lender will not fund construction against a contract that is not effective, and the contract cannot become effective until the construction financing is in place. Something has to break the tie, usually a creditworthy guarantor or a supplier with an interest in the deal landing.
Fermi signed a credit support agreement with AMD in October to help fund the 222 megawatt development. The closing condition stayed open anyway. Support from a chip supplier is not the same as a committed loan facility, and the distinction is exactly what the deadline exposed.
For TensorWave the clock matters. It is an AMD-based neocloud, and its 222 megawatts are due inside the second half of 2027. Construction has to start well before that date, so every quarter the close slips moves the ramp with it.
What to ask before you count a megawatt somebody else signed
Four questions separate contracted capacity from a slide. Which closing conditions are still open, and who waives them? Who guarantees the lease, and what is their rating? What event starts the rent clock? And what does your ramp look like if the closing slips two quarters?
None of this means the capacity will never exist. Fermi and TensorWave both say they are committed, and the lease allows for that. It means the megawatts on a term sheet are worth the conditions attached to them, and those conditions belong in your own capacity plan, not only in the developer’s filing.
Three questions worth carrying into your next capacity review. Which of your committed megawatts sit behind an unmet condition? If your supplier’s financing slipped a quarter, what breaks first? And who in your organization is reading the closing conditions rather than the press release?
Related reading. Broadcom and Intel say money, not chips, is the AI bottleneck now, and Microsoft’s capex miss was a delivery date, not a demand signal.
Get the next one before it is old news
Independent analysis of cloud-native infrastructure, Kubernetes and data center economics. No vendor spin.
[…] Fermi America has $1.5 billion of construction in the ground at Project Matador and no rent coming off it. Its 222 megawatt lease with TensorWave had still not taken effect when the 31 October closing date went by, and the largest open condition is project financing. […]