

Executive Summary
Sidero Labs, the company behind Talos Linux and the Omni fleet manager, was acquired by Yardi Systems for an undisclosed sum on 14 September. Yardi is a privately held real estate software vendor with more than 10,000 employees, no outside investors, and a Talos fleet already running in production. The same announcement added Talos Hypervisor, a native hypervisor built into the operating system.
Together the two moves answer the objection that has capped Talos adoption. Enterprises worried the vendor was too small to back their infrastructure, and that a future owner might close the source. Yardi removes the size objection, and the license stays at MPL-2.0. The hypervisor removes a second objection, that running virtual machines meant adopting Kubernetes first. Talos is still a small player in a market where Broadcom keeps handing it reasons to grow.
Two things landed on the same day from Sidero Labs. The company behind Talos Linux was acquired by Yardi Systems. And Talos Linux gained a hypervisor, shipped as part of the operating system rather than as a product beside it.
Neither move is a surprise on its own. Together they describe the shape of the post-Broadcom virtualization market.
The exit pitch now covers VMs and containers on one host
Buyers leaving a legacy hypervisor keep hitting the same fork. Run Kubernetes and virtual machines on separate platforms with separate teams, or adopt a stack that makes Kubernetes the only way to run a VM. Both are expensive in staff time, and neither is what a VMware administrator wants to hear.
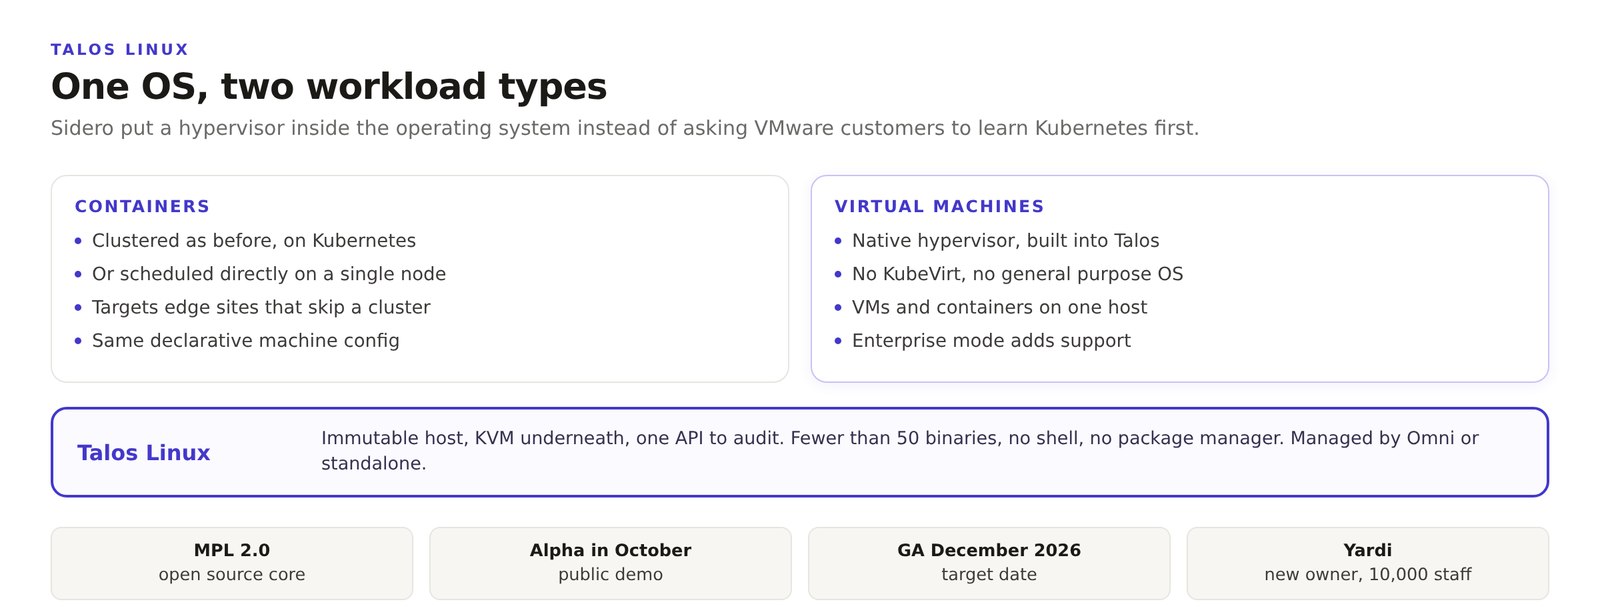
Talos takes a third position. The hypervisor lives inside the immutable host, so a platform team can run VMs and containers on one machine and manage both through the same declarative config and the same mTLS API it already audits. There is no KubeVirt layer to learn, and no general purpose Linux underneath to patch. Sidero calls that the difference between one platform and two, which is the same argument every virtualization challenger has been making since 2024.
The availability numbers are worth stating plainly. Talos Hypervisor is open source under MPL-2.0. The alpha build and a first public demo arrive in October, with general availability targeted for December 2026. An enterprise edition adds support and supply chain assurance on an identical host, a licensing pattern the market already understands.
That timing matters for planning. December 2026 is late enough that nobody migrating off vSphere this quarter can wait for it, and early enough to land inside most multi-year exit programmes.
Running containers without Kubernetes is the quieter change
The second half of the release is easier to miss. Talos can now schedule containers directly on a single node, with no Kubernetes underneath.
That sounds like a step backwards for a Kubernetes company. It is not. Plenty of edge sites run one machine. A retail location, a factory floor gateway, a cell site. A control plane on a single node is overhead with no benefit, on hardware that is already tight on resources. Letting the same OS run a container locally, then join a cluster later when the site grows, keeps one lifecycle instead of two.
An acquisition by a real estate software vendor is the real signal
Yardi is not an infrastructure company. It builds real estate software, has done so for four decades, and runs Talos in its own estate. That is the whole logic of the deal.
Sidero was direct about the problem it solves. Enterprise buyers told the company it was too small and risky to adopt, then asked what would happen if an acquirer killed the product. The announcement answers both questions. Yardi is profitable, privately held, and bought a platform it already depended on. Talos stays open source under MPL-2.0, and the repositories and licensing are unchanged.
Open source communities have learned to watch acquisitions for license changes, and they are right to. The counter-signal here is that the buyer was already a customer. When the acquirer runs the software in production, the incentive to keep it alive is a business case rather than a promise.
Related reading. Our breakdown of the 2026 VMware licensing changes explains the cost pressure that created this market. And the virtualization shortlist is where Talos wants to appear next.
Get the next one before it is old news
Independent analysis of cloud-native infrastructure, Kubernetes and data center economics. No vendor spin.